
15 min read
Annuity Tax Implications: What Happens To Your Money and Your Heirs
Written on January 22, 2026 By Ron McVaney
Ready to start investing in Texas real estate?
Book Your Free Call Today
When evaluating annuities, most investors focus on the promised returns and guaranteed income. What they often overlook are the significant tax implications that can dramatically reduce their net benefits and the complex scenarios that unfold when annuity owners die.
Understanding annuity tax implications and what happens to annuities when you die is essential for accurate retirement and estate planning. The tax treatment of annuities differs significantly from other investments, and these differences can cost you and your heirs tens of thousands of dollars or more.
This comprehensive guide explains how the IRS treats annuity income, why the tax treatment is often unfavorable compared to alternatives, and exactly what your beneficiaries will face when you die.
Tax-Deferred Growth: The Primary Benefit
The most promoted benefit of annuities is tax-deferred growth. During the accumulation phase while your money grows inside the annuity, you don't pay taxes on interest, dividends, or capital gains as they accumulate.
This allows your money to compound without the annual tax drag you'd experience in a taxable brokerage account where you pay taxes on dividends, interest, and realized capital gains each year.
Who Benefits Most from Tax Deferral
Tax deferral provides the greatest value for:
High-income earners in top tax brackets (32%, 35%, or 37%) who would otherwise pay substantial annual taxes on investment earnings
Investors who have maxed out other tax-advantaged accounts like 401(k)s, IRAs, and HSAs and want additional tax-deferred growth opportunities
Long time horizons of 20+ years that allow compounding benefits to outweigh the higher fees annuities charge
The Trade-Off Nobody Mentions
While tax deferral sounds appealing, it comes with a significant trade-off: all earnings are eventually taxed as ordinary income at your highest marginal tax rate, not at the more favorable long-term capital gains rates.
This trade-off often makes tax deferral less valuable than it initially appears, especially when you factor in the high fees that annuities charge.
Ordinary Income Tax Treatment: The Major Drawback
Here's where annuity tax implications become problematic: all earnings are taxed as ordinary income when withdrawn, regardless of whether those earnings came from interest, dividends, or capital appreciation.
Comparing Tax Rates
The tax difference is substantial:
Long-term capital gains tax rates: 0%, 15%, or 20% (based on income level)
Ordinary income tax rates: 10%, 12%, 22%, 24%, 32%, 35%, or 37%
If you're in the 24% tax bracket, you'll pay 24% on annuity earnings versus 15% on long-term capital gains from stocks held over a year. For someone in the 32% bracket, the difference is even more stark: 32% versus 15%.
The Long-Term Impact
Over decades, this tax differential can cost you tens or hundreds of thousands of dollars.
Example:
You invest $200,000 that grows to $500,000 over 20 years, generating $300,000 in gains.
In an annuity (24% tax bracket):
Tax on withdrawal: $300,000 x 24% = $72,000
Net after taxes: $428,000
In a taxable brokerage account (15% long-term capital gains rate):
Tax on gains: $300,000 x 15% = $45,000
Net after taxes: $455,000
The taxable account leaves you with $27,000 more despite paying taxes annually along the way. When you factor in the higher fees that annuities charge (typically 2-3% annually versus 0.05-0.20% for index funds), the advantage of the taxable account grows even larger.
LIFO Taxation: Last In, First Out
Non-qualified annuities (purchased with after-tax dollars) use LIFO taxation, which stands for "last in, first out." This means withdrawals come from earnings first, then from your principal.
How LIFO Works
Assume you invest $100,000 in a non-qualified annuity and it grows to $150,000, generating $50,000 in earnings.
If you withdraw $30,000:
- The first $30,000 comes entirely from your $50,000 in earnings
- All $30,000 is taxable as ordinary income
- Your principal remains untouched
If you withdraw $60,000:
- The first $50,000 comes from earnings (fully taxable)
- The next $10,000 comes from principal (not taxable, since you already paid taxes on it)
Why LIFO Hurts You
LIFO taxation accelerates your tax liability. Every withdrawal triggers immediate taxation on gains, giving you no control over when to realize income.
Compare this to a taxable brokerage account where you can:
- Choose which specific investments to sell
- Harvest tax losses to offset gains
- Hold appreciated positions indefinitely, deferring taxes
- Pass appreciated assets to heirs with a step-up in cost basis
Annuities offer none of this flexibility. LIFO forces the least tax-efficient withdrawal order possible.
Qualified vs Non-Qualified Annuities: Tax Treatment Differences
Understanding the distinction between qualified and non-qualified annuities is essential for evaluating annuity tax implications.
Non-Qualified Annuities
Non-qualified annuities are purchased with after-tax dollars (money you've already paid income taxes on).
Tax treatment:
- Principal contributions are not taxable when withdrawn (you already paid taxes)
- Only earnings are taxable as ordinary income
- LIFO taxation applies (earnings come out first)
- No required minimum distributions during your lifetime
- More flexibility in timing withdrawals for tax planning
Qualified Annuities
Qualified annuities are held inside tax-advantaged retirement accounts like IRAs or 401(k)s. You fund them with pre-tax dollars.
Tax treatment:
- All withdrawals are taxed as ordinary income (you haven't paid taxes on any of it yet)
- Subject to required minimum distributions starting at age 73
- 10% IRS early withdrawal penalty applies before age 59½ (with limited exceptions)
- Less flexibility due to RMD requirements
The Qualified Annuity Question
Placing an annuity inside an IRA or 401(k) adds layers of fees and restrictions to an already tax-advantaged account. You're paying annuity fees (often 2-3% annually) for tax deferral you already have through the IRA itself.
This rarely makes sense. If you want guaranteed income in retirement, consider purchasing an immediate annuity with IRA funds at retirement, not decades earlier. The long surrender periods and high fees during accumulation years typically outweigh any benefits.
Additional Tax Considerations
Beyond ordinary income treatment and LIFO taxation, several other tax issues affect annuity owners.
Net Investment Income Tax (NIIT)
High-income earners may owe an additional 3.8% Net Investment Income Tax on annuity earnings. This applies if your modified adjusted gross income exceeds:
$250,000 for married filing jointly
$200,000 for single filers
$125,000 for married filing separately
When combined with ordinary income tax rates, high earners could pay over 40% in federal taxes alone on annuity withdrawals, making these products particularly tax-inefficient for wealthy individuals.
State Income Taxes
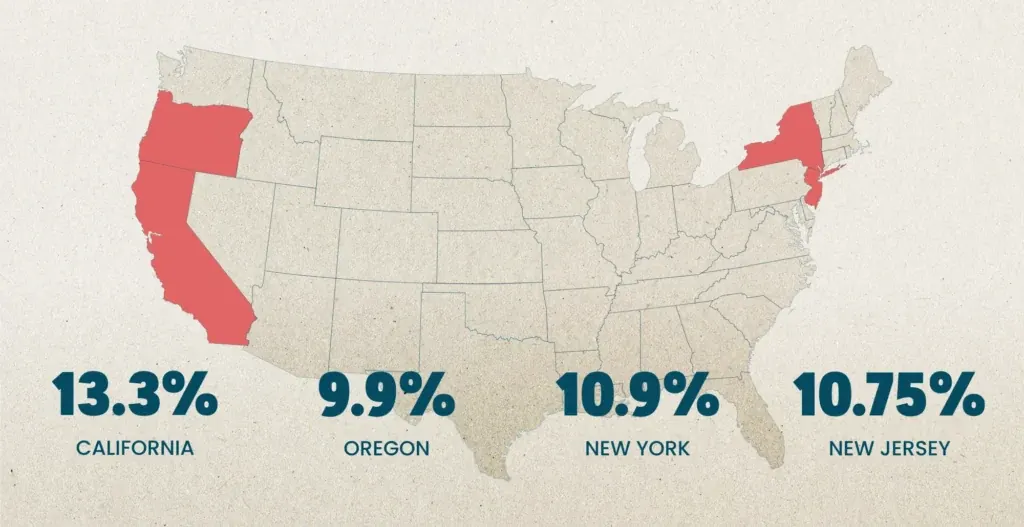
Don't forget state income taxes. Most states tax annuity withdrawals as ordinary income. If you live in a high-tax state, your combined federal and state tax burden can be severe:
California: Up to 13.3% state tax
New York: Up to 10.9% state tax
New Jersey: Up to 10.75% state tax
Oregon: Up to 9.9% state tax
A California resident in the 32% federal bracket could pay over 45% combined taxes on annuity earnings (32% federal + 13.3% state). Several states offer preferential treatment for long-term capital gains and qualified dividends, but not for annuity withdrawals.
No Tax-Loss Harvesting
In taxable accounts, you can harvest tax losses by selling declining investments to offset gains, reducing your tax bill. Annuities offer no such opportunity. Whether your annuity investments perform well or poorly, you'll owe ordinary income taxes on any net gains when you withdraw.
What Happens to Annuities When You Die
Understanding what happens to annuities when you die is crucial for estate planning. The treatment varies significantly based on timing, beneficiary designation, and the type of annuity.
Death During Accumulation Phase
If you die before annuitizing (converting to income payments), your beneficiary typically receives the account value or a guaranteed death benefit, depending on your contract terms.
Standard Death Benefit
Most annuities provide a death benefit equal to the greater of:
- Current account value
- Total premiums paid (return of premium guarantee)
This protects beneficiaries if your annuity has lost value, though the fees you paid along the way are never recovered.
Enhanced Death Benefit Riders
Some annuities offer optional death benefit riders (at additional annual cost of 0.25% to 1.5% or more) that guarantee beneficiaries receive:
- Highest account value on any policy anniversary
- Initial investment plus a set percentage (such as 5% annually)
- Some other enhanced amount
These riders provide additional protection but further increase the already high cost of annuities. Calculate whether the additional premium is worth the extra protection, especially if you're young and healthy.
Death After Annuitization
Once you've converted your annuity to lifetime income payments, what happens at death depends entirely on the payout option you selected at annuitization.
Life Only (Single Life)
Payments stop immediately upon death. Your beneficiaries receive nothing, regardless of how long you received payments. If you annuitized $500,000, received two monthly payments totaling $5,000, and then died, the insurance company keeps the remaining $495,000.
This option provides the highest monthly payment during your life but is the most financially risky for your heirs.
Life with Period Certain
Payments continue for your life, but if you die within the certain period (commonly 10 or 20 years), your beneficiary receives payments for the remainder of that period.
Example: You choose life with 20-year period certain and die after 8 years. Your beneficiary receives payments for the remaining 12 years.
Joint and Survivor
Payments continue as long as either you or your spouse is alive. The payment amount for the survivor is either the same as the original payment or a reduced amount (such as 50%, 66%, or 75% of the original).
This protects your spouse but typically results in lower initial payments than single-life options.
Installment Refund or Cash Refund
If you die before receiving payments equal to your initial investment, your beneficiary receives the remaining balance either in continued installments (installment refund) or as a lump sum (cash refund).
Beneficiary Tax Treatment: Often Worse Than Expected
Beneficiaries who inherit annuities face significant and often surprising tax consequences.
Spouse Beneficiaries
Surviving spouses have the most flexibility:
Continue the Annuity
The spouse can treat the annuity as their own, maintaining tax deferral and avoiding immediate taxation. They become the new owner and can name their own beneficiaries.
Take Distributions
The spouse can withdraw funds over their life expectancy, spreading the tax burden over many years, or take a lump sum and pay all taxes immediately.
Annuitize
The spouse can convert the annuity to lifetime income payments based on their age.
Non-Spouse Beneficiaries
Non-spouse beneficiaries (children, siblings, friends, trusts) face more restrictive rules and typically have two main options:
Lump Sum Distribution
Take the entire amount immediately. All earnings are taxable as ordinary income in the year received. This can create a massive tax bill and potentially push the beneficiary into a higher tax bracket.
Example: Your adult child inherits a $400,000 annuity with $150,000 in earnings. They must pay ordinary income tax on $150,000. In the 24% tax bracket, that's $36,000 in federal taxes, plus state taxes.
Five-Year Rule
Withdraw the entire balance within five years of death. This provides some flexibility to spread the tax burden across multiple years, but still requires complete distribution relatively quickly.
Stretch Provisions (Limited)
Some older annuity contracts allowed non-spouse beneficiaries to stretch distributions over their life expectancy. The SECURE Act of 2019 eliminated most stretch provisions for non-spouse beneficiaries, though some exceptions exist for eligible designated beneficiaries (minor children, disabled or chronically ill individuals, and beneficiaries not more than 10 years younger than the deceased).
The Tax Burden Problem
The tax treatment of inherited annuities is often much less favorable than other inherited assets:
Stocks and Real Estate: Beneficiaries receive a step-up in cost basis to the date-of-death value, potentially eliminating capital gains taxes entirely.
Roth IRAs: Beneficiaries receive distributions tax-free (though they must withdraw the full balance within 10 years under current rules).
Annuities: All earnings are taxed as ordinary income to beneficiaries, often creating substantial tax bills at the worst possible time (while grieving and managing an estate).
This tax inefficiency makes annuities poor estate planning vehicles compared to alternatives.
Estate Tax Considerations
Annuities are included in your taxable estate at their full value. For 2024, the federal estate tax exemption is $13.61 million per individual ($27.22 million for married couples). Most people won't owe federal estate taxes, but those with large estates face a significant issue.
Double Taxation
For estates exceeding the exemption threshold, annuities can be subject to both estate tax (up to 40%) and income tax when beneficiaries withdraw the funds.
Example:
Estate subject to federal estate tax includes a $1 million annuity with $400,000 in earnings.
Estate tax on annuity (40%): $400,000
Remaining value to beneficiary: $600,000
Income tax on $400,000 earnings (24% bracket): $96,000
Net to beneficiary after both taxes: $504,000
This double taxation makes annuities particularly inefficient for large estates. Life insurance, by contrast, provides income-tax-free death benefits and can be structured to avoid estate taxes through irrevocable life insurance trusts.
Planning Strategies to Minimize Tax Impact
If you own an annuity or are considering one, these strategies can help minimize tax consequences:
Name Your Spouse as Primary Beneficiary
This provides maximum flexibility and allows the surviving spouse to continue tax deferral, potentially converting the annuity to a more favorable product or withdrawing funds strategically to minimize taxes.
Consider Systematic Withdrawals During Your Lifetime
Rather than leaving a large annuity to non-spouse beneficiaries who'll face immediate taxation, consider taking systematic withdrawals during your lifetime when you might be in a lower tax bracket. This strategy is especially valuable if you're retired and in the 12% or 22% bracket, versus your working adult children who might be in the 24%, 32%, or higher brackets.
Review Beneficiary Designations Regularly
Ensure your beneficiary designations reflect your current wishes and family situation. Annuity beneficiary designations override your will, so outdated designations can cause unintended consequences.
Life changes that should trigger beneficiary reviews include:
- Marriage or divorce
- Birth or adoption of children
- Death of a named beneficiary
- Significant changes in family circumstances
- Changes in tax laws
Evaluate Death Benefit Riders Carefully
Enhanced death benefit riders cost money annually. Calculate whether the additional cost is worthwhile based on:
- Your age and health
- The size of the death benefit enhancement
- Alternative ways to protect your heirs (like term life insurance)
- Whether you have other assets to leave to beneficiaries
For young, healthy individuals, term life insurance often provides more death benefit protection per dollar of premium than annuity death benefit riders.
Consider the Tax Efficiency of Alternatives
For estate planning purposes, compare annuities to alternatives:
Life Insurance: Death benefits are generally income-tax-free to beneficiaries and can be structured to avoid estate taxes.
Roth IRA Conversions: Pay taxes now at potentially lower rates, leaving tax-free Roth assets to heirs.
Appreciated Securities: Beneficiaries receive a step-up in cost basis, eliminating capital gains taxes.
Real Estate: Also receives a step-up in basis, plus potential for ongoing income and appreciation.
Questions to Ask About Tax Implications and Death Benefits
Before purchasing an annuity, get clear answers about tax treatment and what happens when you die:
1. How will withdrawals be taxed in my specific situation (ordinary income, capital gains, etc.)?
2. What is my effective tax rate on annuity withdrawals including federal, state, and NIIT?
3. How does this compare to the tax treatment of alternative investments?
4. What exactly happens to my annuity if I die during the accumulation phase?
5. What options will my beneficiaries have, and what taxes will they owe?
6. If I annuitize, what payout options protect my beneficiaries, and how much do those options reduce my payment?
7. Are there enhanced death benefit riders available, what do they cost, and are they worthwhile?
8. How does the tax treatment of this annuity compare to leaving other assets to my heirs?
9. Will my annuity be subject to both estate tax and income tax?
10. Can you show me projections of after-tax returns compared to alternatives?
Demand specific, written answers. If the salesperson can't clearly explain the tax implications and death benefit scenarios, that's a major red flag.
Real-World Scenario: The Total Tax Impact
Let's examine a comprehensive example showing the total tax impact over a lifetime and at death.
You invest $300,000 in a variable annuity at age 50. It grows to $750,000 by age 75 when you begin taking withdrawals. You're in the 24% federal tax bracket and California's 9.3% state bracket (33.3% combined).
During Your Lifetime:
You withdraw $50,000 annually for 10 years.
Total withdrawals: $500,000
Earnings portion subject to tax: $450,000 (everything above your $300,000 basis)
Federal tax (24%): $108,000
State tax (9.3%): $41,850
Total taxes paid: $149,850
At Death:
Remaining annuity value: $400,000
Your basis remaining: $150,000 (you recovered $150,000 of principal)
Earnings in remaining balance: $250,000
Your non-spouse beneficiary faces:
Income tax on $250,000 at 32% federal + 9.3% California = $103,250
Total Family Tax Bill:
Taxes during your lifetime: $149,850
Taxes to beneficiary: $103,250
Combined taxes: $253,100
Compare to a Taxable Brokerage Account:
Same $300,000 investment growing to $750,000
Long-term capital gains tax during withdrawals (15%): $67,500
Beneficiary receives step-up in basis: $0 additional taxes
Combined taxes: $67,500
The annuity resulted in $185,600 more in taxes, plus you paid higher annual fees (2.5% vs 0.1%) which would add another $100,000+ in costs over 25 years.
The Bottom Line on Annuity Tax Implications
Annuity tax implications are often far less favorable than investors realize when they purchase these products. The combination of ordinary income tax treatment, LIFO taxation, lack of tax planning flexibility, and unfavorable treatment for beneficiaries makes annuities tax-inefficient for most investors.
While tax deferral sounds appealing in the sales presentation, the reality is that you're simply postponing taxes and potentially paying them at higher rates (ordinary income rather than capital gains). When you factor in the high fees, limited liquidity, and estate planning disadvantages, the tax benefits rarely justify the costs.
Understanding what happens to annuities when you die reveals another layer of tax inefficiency. Unlike stocks, bonds, or real estate that receive favorable tax treatment for heirs, annuities burden beneficiaries with immediate income tax liability on all earnings, often at the worst possible time.
Before committing funds to an annuity, carefully analyze:
- Your current and expected future tax brackets
- How annuity withdrawals will be taxed versus alternatives
- The after-tax returns over your expected holding period
- The tax burden you'll leave to beneficiaries
- Whether the tax deferral is worth the fees, restrictions, and ultimate tax treatment
For most investors, a diversified portfolio of low-cost index funds, municipal bonds, and other tax-efficient investments provides better after-tax returns, more flexibility, lower fees, and more favorable estate planning outcomes than annuities.
Your retirement security and your legacy to heirs deserve better than a product that generates large commissions for salespeople while delivering disappointing after-tax results for you and substantial tax bills for your beneficiaries.
If you’d like to learn more about the options and alternatives available to you right now, go ahead and book a no-obligation call with one of our investor acquisition assistants.
Important Disclosure: This article is for educational purposes only and does not constitute financial or tax advice. Past performance does not guarantee future results. All investments carry risk. Please consult with a qualified financial professional before making investment decisions.