
14 min read
Annuity Surrender Fees Explained: Understanding Withdrawal Penalties and Restrictions
Written on February 01, 2026 By Ron McVaney
Ready to start investing in Texas real estate?
Book Your Free Call Today
When financial advisors pitch annuities, they emphasize guaranteed income and tax-deferred growth. What they often downplay are the substantial penalties and restrictions that come with these products. Understanding annuity surrender fees and withdrawal rules is critical before you commit what might be hundreds of thousands of dollars to a contract that could lock up your money for a decade or more.
This comprehensive guide breaks down the real costs of accessing your money early, the complex withdrawal rules you'll face, and the strategies for managing or avoiding these expensive restrictions.
What Are Annuity Surrender Fees?
Annuity surrender fees (also called surrender charges or withdrawal penalties) are penalties imposed by insurance companies when you withdraw more than a specified amount from your annuity during the surrender period.
Think of surrender fees as the insurance company's way of recouping the commissions they paid to the salesperson who sold you the annuity, plus ensuring they have your money long enough to profit from it.
These fees can be substantial, often ranging from 5% to 10% or more of the amount you withdraw. For a $200,000 investment, an early withdrawal could cost you $10,000 to $20,000 in surrender charges alone, before accounting for taxes or IRS penalties.
How Surrender Charges Work
When you purchase an annuity, you enter into a contract that typically includes a surrender period lasting anywhere from 5 to 10 years, though some extend to 15 years or longer. During this period, withdrawing funds beyond the allowed "free withdrawal" amount triggers surrender charges.
Typical Surrender Charge Schedule
Here's a typical surrender charge schedule for a 10-year annuity:
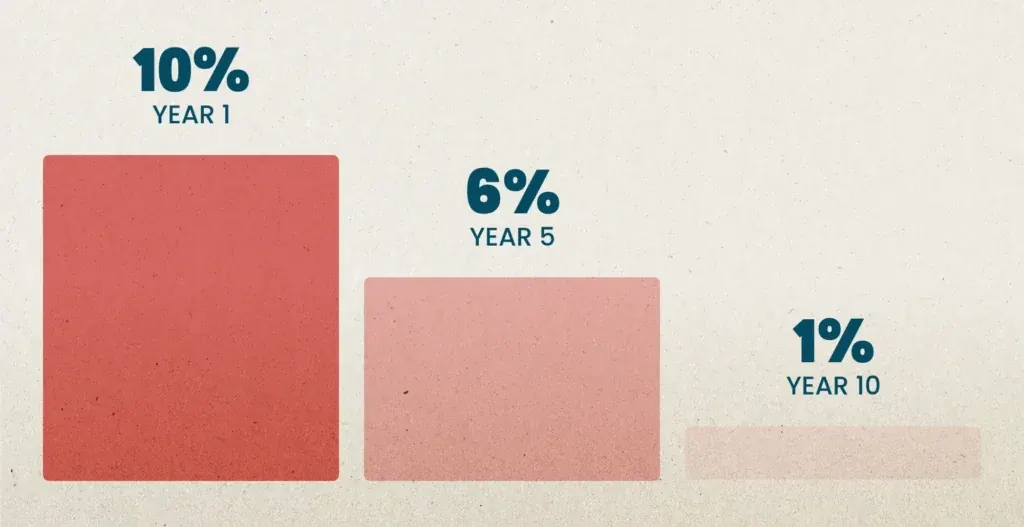
Year 1: 10% surrender charge
Year 2: 9% surrender charge
Year 3: 8% surrender charge
Year 4: 7% surrender charge
Year 5: 6% surrender charge
Year 6: 5% surrender charge
Year 7: 4% surrender charge
Year 8: 3% surrender charge
Year 9: 2% surrender charge
Year 10: 1% surrender charge
Year 11+: 0% surrender charge
This means if you invest $100,000 and need to withdraw it all in Year 3, you'd pay $8,000 in surrender charges, receiving only $92,000 (before taxes and any IRS penalties).
Some annuities use a flat surrender charge that remains constant for several years before dropping. Others use more aggressive schedules with higher initial penalties. Always ask for the specific surrender schedule in writing before purchasing.
Why the Schedule Decreases Over Time
The declining surrender charge reflects the insurance company's decreasing need to recoup costs. In the early years, they're still recovering the upfront commission paid to the salesperson and haven't had enough time to profit from managing your money. As years pass and they've recouped their costs, the penalty decreases until it eventually disappears.
Why Surrender Fees Exist
Insurance companies impose surrender fees for several specific reasons:
Commission Recovery
When you purchase an annuity, the salesperson typically receives a commission of 5% to 8% or more of your investment. The insurance company pays this upfront and recoups it through the fees they charge you over time. Surrender charges ensure they recover these costs even if you leave early.
This creates a fundamental conflict of interest. The person recommending the annuity may be more motivated by earning a $5,000 to $8,000 commission on a $100,000 sale than by what's truly best for your financial future.
Investment Strategy Protection
Insurance companies invest your money in longer-term assets to generate returns. They promise you certain rates or income, and they need time to make those investments profitable. Early withdrawals force them to liquidate investments prematurely, potentially at a loss. Surrender charges compensate for this disruption.
Profit Assurance
Insurance companies make money by keeping your funds invested and earning more on their investments than they pay you. The longer they have your money, the more they profit. Surrender charges ensure minimum profitability even if you don't keep your money with them as long as they'd prefer.
Free Withdrawal Provisions: The 10% Rule
Most annuities include a "free withdrawal" provision that allows you to withdraw up to 10% of your account value annually without surrender charges. Some contracts offer more generous terms, while others are more restrictive.
How Free Withdrawals Work
The free withdrawal amount is typically calculated in one of two ways:
10% of your initial premium (the amount you originally invested)
10% of your current account value
These can produce significantly different results. If your $100,000 investment has grown to $130,000, the first method allows $10,000 annual withdrawals while the second allows $13,000.
Important Caveats About Free Withdrawals
Non-Cumulative
The 10% is typically annual, not cumulative. You can't skip a year and then withdraw 20% the following year without penalties. Use it or lose it.
No IRS Protection
Free withdrawals don't protect you from IRS penalties if you're under age 59½. You'll still owe the 10% early withdrawal penalty to the IRS plus ordinary income taxes on any earnings, even though you avoided the insurance company's surrender charge.
Contract Year vs Calendar Year
Some annuities reset the free withdrawal amount each contract year (based on your purchase anniversary), while others use the calendar year. This timing detail matters significantly when planning withdrawals.
Withdrawal Order
Remember that withdrawals from non-qualified annuities come from earnings first (LIFO taxation), meaning even "free" withdrawals trigger immediate tax liability on gains.
The Real Cost of Surrender Charges: Detailed Examples
Let's examine the true financial impact with realistic scenarios that show how quickly costs accumulate.
Scenario 1: Emergency Withdrawal in Year 3
You invest $200,000 in a variable annuity with a 10-year surrender period. Three years later, you face unexpected medical expenses and need access to your funds. Your account has grown to $220,000.
Year 3 surrender charge: 8%
Surrender penalty: $220,000 x 8% = $17,600
But the costs don't stop there:
IRS early withdrawal penalty (if under 59½): $220,000 x 10% = $22,000
Ordinary income tax on $20,000 gain (assuming 24% tax bracket): $4,800
Total penalties and taxes: $44,400
Amount you actually receive: $175,600
You invested $200,000 and received $175,600, a loss of $24,400, despite your account growing by $20,000. This demonstrates why liquidity matters and why locking up money you might need is so dangerous.
Scenario 2: Partial Withdrawal Beyond Free Amount
You have $150,000 in an annuity (Year 4, with 7% surrender charge) and need $30,000 for a home down payment.
Free withdrawal amount (10%): $15,000
Amount subject to surrender charge: $15,000
Surrender charge: $15,000 x 7% = $1,050
IRS penalty on $15,000 over free amount (if under 59½): $1,500
Taxes on earnings portion: Variable based on your tax bracket
Even a partial withdrawal beyond the free amount triggers substantial penalties. Many investors don't realize the free withdrawal provision doesn't eliminate surrender charges, it just creates a penalty-free corridor.
Scenario 3: The Long-Term Lock-Up
You purchase an annuity at age 50 with a 10-year surrender period. You can't access your full balance without penalties until age 60. If you need the money at age 55 for any reason (job loss, business opportunity, family emergency), you'll pay dearly.
This long-term lock-up is particularly problematic because life is unpredictable. The "guaranteed" income annuities promise means nothing if you can't access your money when you need it most.
Annuity Withdrawal Rules: Beyond Surrender Charges
Surrender charges are just one layer of restrictions. Annuities come with complex withdrawal rules that further limit your access to funds.
IRS Early Withdrawal Penalties
Separate from insurance company surrender charges, the IRS imposes its own 10% penalty on annuity withdrawals taken before age 59½. This applies to the earnings portion of your withdrawal, not the principal you invested with after-tax dollars (in non-qualified annuities).
The IRS treats annuities as retirement savings vehicles and penalizes early access just like they do with 401(k)s and IRAs.
Exceptions to the 10% IRS Penalty
Limited exceptions exist:
Death or total and permanent disability
Substantially equal periodic payments (SEPP) under IRS Rule 72(t), which requires you to take calculated payments for at least 5 years or until age 59½, whichever is longer
Immediate annuities that begin payments within one year of purchase
Qualified annuities used for certain medical expenses exceeding 7.5% of adjusted gross income
These exceptions are narrow and come with strict requirements. The SEPP exception, for example, locks you into a payment schedule you can't alter without triggering all the penalties you avoided, plus interest.
Most people who need money before 59½ will pay both surrender charges and IRS penalties, creating a double penalty that can consume 20% or more of their withdrawal.
Required Minimum Distributions
If your annuity is held in a qualified retirement account (IRA, 401(k), etc.), you must begin taking required minimum distributions at age 73 (as of 2024). The RMD amount is calculated based on your account balance and IRS life expectancy tables.
Failure to take your RMD results in a substantial IRS penalty: 25% of the amount you should have withdrawn (reduced to 10% if corrected within two years). This penalty applies even if you don't need the income, forcing you to take taxable distributions whether you want them or not.
For non-qualified annuities (purchased with after-tax dollars), RMDs don't apply during your lifetime, giving you more control over withdrawal timing.
Systematic Withdrawal Plans
Many annuities offer systematic withdrawal plans that allow you to receive regular payments without annuitizing (converting to lifetime income). These withdrawals are typically subject to:
The free withdrawal provisions (usually 10% annually without surrender charges)
IRS penalties if under age 59½
Ordinary income taxation on earnings
Systematic withdrawals provide more flexibility than annuitization because you maintain access to your principal (subject to surrender charges during the surrender period). However, they don't provide the lifetime income guarantee that annuitization offers.
Annuitization: The Irreversible Decision
When you annuitize, you convert your annuity's account value into a stream of payments. This decision is typically irrevocable and represents the most restrictive withdrawal rule of all.
What Happens When You Annuitize
Once you annuitize:
You no longer have access to your principal lump sum
You can't change payment amounts or frequency
Your payment structure is locked in permanently
You can't reverse the decision if circumstances change
What happens to remaining funds at death depends on the payout option you selected
If you choose a life-only payout (the highest monthly payment option) and die shortly after annuitizing, the insurance company keeps all remaining funds. Your heirs receive nothing, even if you annuitized $500,000 and received only $10,000 in payments.
When Annuitization Might Make Sense
Despite the restrictions, annuitization serves a purpose for certain investors:
You're concerned about outliving your assets and want guaranteed lifetime income
You lack the discipline to manage systematic withdrawals
You have other liquid assets for emergencies
You're in poor health and choose a period certain or joint payout that protects beneficiaries
You fully understand and accept the irreversibility
Even in these situations, only annuitize a portion of your retirement savings. Maintaining liquidity in other accounts provides flexibility for unexpected needs.
The Questions to Ask Before Committing of Texas Real Estate
Before purchasing an annuity, get clear answers to these critical questions about fees and restrictions:
1. What is the exact surrender charge schedule, year by year, in writing?
2. What percentage can I withdraw annually without surrender charges?
3. How does the free withdrawal provision work specifically (contract year vs calendar year, based on premium or account value)?
4. Can I take multiple withdrawals in a year within the free amount, or is it one withdrawal only?
5. What happens to the surrender schedule if I exchange this annuity for another (1035 exchange)?
6. If I die during the surrender period, do my beneficiaries face surrender charges?
7. What are the specific exceptions that would allow me to withdraw funds without surrender charges?
8. How does the systematic withdrawal plan work, and what are its limitations?
9. Once I annuitize, can I ever reverse that decision or access my principal?
10. Can you provide examples showing the total cost (surrender charges + IRS penalties + taxes) of withdrawing funds in years 1, 3, 5, and 10?
Get all answers in writing as part of the contract or in a separate disclosure document. Never rely on verbal promises or assurances.
Exit Strategies: Already Stuck in an Annuity
If you're already in an annuity with high surrender charges and regret the decision, you have several options:
Wait Out the Surrender Period
If you're close to the end of the surrender period (2-3 years remaining), waiting may be the most cost-effective option. Calculate the fees you'd pay to exit early versus the fees you'll pay by staying, factoring in the difference in performance between your annuity and alternative investments.
Use Free Withdrawal Provisions Strategically
Take advantage of the annual free withdrawal amount (typically 10%) to gradually reduce your exposure without penalties. If you have $200,000 in an annuity, you can withdraw $20,000 per year penalty-free, completely exiting over 10 years.
This strategy works well if:
You don't need all the money immediately
You're comfortable keeping a declining balance in the annuity
The surrender period is long, making early exit prohibitively expensive
1035 Exchange to a Better Annuity
Section 1035 of the tax code allows you to exchange one annuity for another without tax consequences. This can help if you want to move to an annuity with:
Lower annual fees
Shorter surrender period
Better investment options
More favorable terms
The critical caveat: a 1035 exchange typically starts a new surrender period. You're escaping one set of restrictions only to enter another, though hopefully with better overall terms. This only makes sense if the new annuity is significantly better than your current one.
Evaluate Whether Paying the Surrender Charge Makes Sense
Sometimes paying the surrender charge to get into a lower-cost investment makes financial sense over the long term. Calculate the break-even point.
Example:
$200,000 in an annuity with 2.5% annual fees
6 years remaining on surrender period with 6% surrender charge
Surrender charge cost: $12,000
Alternative: Index fund with 0.05% annual fees
Annual fee savings: $4,900
Break-even point: 2.4 years
If you're confident you won't need the money for 3+ years, paying the $12,000 surrender charge to save $4,900 annually makes mathematical sense. After 6 years, you'd be ahead by nearly $18,000 despite paying the upfront penalty.
Run these calculations with your specific numbers, factoring in:
Remaining surrender charges
Annual fee differences
Tax implications
Your age relative to 59½ (IRS penalty considerations)
Your expected time horizon
Consider Your Age and Tax Situation
If you're under 59½, remember you'll face IRS penalties in addition to surrender charges. Sometimes waiting until 59½ dramatically reduces your total penalties, even if surrender charges remain.
If you're in a high tax bracket now but expect to be in a lower bracket in retirement, waiting might provide tax benefits that offset some surrender charge costs.
Protecting Yourself: Alternatives to Consider
Before committing to an annuity, consider whether these alternatives might serve you better:
Bond Ladders
Create predictable income with far better liquidity and lower costs. No surrender charges, ever.
Dividend Stock Portfolios
Generate growing income that keeps pace with inflation. Complete liquidity and favorable tax treatment.
Systematic Withdrawal Plans from Diversified Portfolios
Create your own "annuity" with full control and no surrender restrictions. Studies show this approach often outperforms annuity purchases.
Land-Backed Investment Funds
For investors seeking passive income with real asset backing, land-backed funds offer monthly distributions with no surrender charges in many structures, plus equity participation in appreciation.
Certificate of Deposit Ladders
FDIC-insured safety with clear terms and reasonable early withdrawal penalties (typically 3-12 months of interest, not 5-10% of principal).
Each alternative provides greater flexibility than annuities while often delivering comparable or superior returns with lower costs.
Red Flags: When to Walk Away
Be extremely cautious if you encounter any of these situations:
The salesperson pressures you to decide immediately
They discourage you from consulting other advisors or family members
The surrender period exceeds 10 years
Surrender charges start above 10% or remain high for many years
The contract is confusing and the salesperson can't clearly explain all terms
You're told "don't worry about the surrender charges, you won't need the money"
The free withdrawal provisions are less generous than 10% annually
The salesperson focuses on returns and downplays liquidity restrictions
You're encouraged to use IRA or 401(k) funds to purchase a qualified annuity (adding annuity fees on top of already tax-deferred accounts)
These red flags often indicate a product designed more to generate commissions than to serve your best interests.
The Bottom Line on Surrender Fees and Withdrawal Rules
Annuity surrender fees and withdrawal rules represent significant barriers to accessing your money when you need it. While insurance companies and salespeople may downplay these restrictions, they can trap you for a decade or more and cost you tens of thousands of dollars if circumstances change.
The surrender charge schedule that looks manageable on paper becomes painfully real when you face a job loss, medical emergency, business opportunity, or any other situation requiring access to your funds. Combined with IRS early withdrawal penalties, the total cost of accessing your money can exceed 20% of your withdrawal amount.
Before committing to an annuity:
Understand every restriction in detail and get them in writing
Calculate the total cost of early withdrawal at various time points
Honestly assess your liquidity needs and how circumstances might change
Compare the after-fee, after-penalty costs to alternative investments
Ensure you have adequate liquid emergency funds outside the annuity
Never invest money you might need within the surrender period
For most investors, the combination of surrender charges, IRS penalties, and withdrawal restrictions makes annuities less attractive than alternatives offering comparable income with better liquidity and lower costs.
Your financial flexibility is valuable. Don't surrender it for a product that locks up your money for years and penalizes you heavily for needing access to funds you've worked hard to accumulate. Make sure any product you choose truly serves your best interests while preserving your ability to adapt to life's uncertainties.
Important Disclosure: This article is for educational purposes only and does not constitute financial advice. Past performance does not guarantee future results. All investments carry risk. Please consult with a qualified financial professional before making investment decisions.